The new insurance protecting apartment buyers
Buyer beware is a label that has been applied to the new apartment sector in Australia, making it a no-go area for many.
Serious building defects combined with high-profile developer insolvencies - Sydney-based Bathla Group is the latest - have turned off many buyers.
But insurance giving apartment buyers 10 years of no-fault cover for serious structural defects is set to be a game changer.
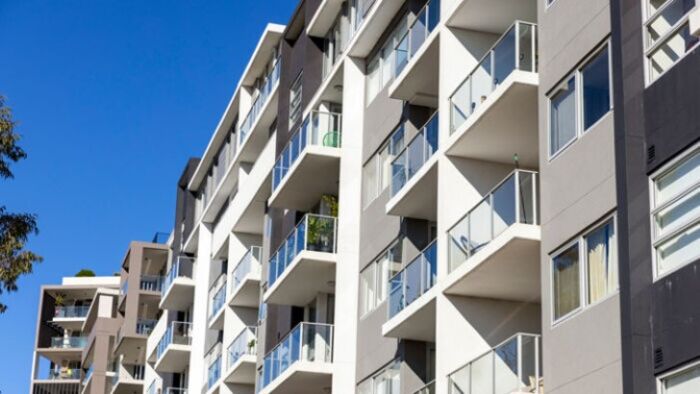
What is Decennial Liability Insurance?
Decennial Liability Insurance (DLI), also known as Latent Defects Insurance (LDI), is relatively new to Australia, but similar schemes have been available overseas for decades.
It covers new apartments whether off-the-plan or newly completed because the policy attaches directly to the building rather than the builder/ developer or the original buyer.
It activates if structural components such as foundations, columns, slabs and load-bearing walls fail and make the property uninhabitable or unsafe, regardless of fault or negligence.
"'Does this apartment come with LDI?' is the one question every new or off-the-plan apartment buyer should ask," says Craig Anderson, executive director of Princeton Financial Services, which operates as a lender and a developer.
"You've got one chance to get it right, so get it right."
This type of insurance originated in France and is available in more than 40 countries. In many, including France, Spain, Italy and Finland, LDI/DLI is mandatory by law for new residential builds.
A developer cannot legally hand over a building, and a bank will not finance it without a policy in place.
By transforming apartment purchases from a gamble on a developer's solvency into an institutionally backed investment, LDI has reshaped real estate markets overseas.
It's viewed as a cornerstone for building buyer and investor confidence by many industry experts.
Could it soon be mandatory?
New South Wales is pushing ahead to make it mandatory for all new apartment buildings by 2028, a move which should improve consumer confidence in the sector.
It recently passed the final piece of legislation enabling DLI, making it the third State to legislate the cover after ACT and Victoria.
Although not legislated in other States and Territories, it is available through national insurance brokers.
Urban Property is credited with being the first developer to buy 10-year insurance cover for defects for a 67-unit development in Bexley in suburban Sydney in 2022.
"We believe the insurance will create a compelling market proposition for buyers looking for developers and builders to stand by their products and protect their customers," CEO Patrick Elias told the Australian Financial Review at the time.
Why buyers are paying attention
Anderson agrees the adoption of LDI is a positive for consumers but fears many buyers still view new apartments as untrustworthy.
"The Building Commission has lifted standards, but this is not widely recognised and most still think buying off-the-plan is not safe," says Anderson.
In NSW, home to about 45% of the country's apartments, he says a widespread education campaign on LDI by the State government would help, especially since more people will need to live in apartments as land near major hubs becomes even scarcer.
A key feature of the insurance is that it attaches to the building, not the company that built it.
This means it survives even if a builder or developer becomes insolvent.
Given the fact that 53% of surveyed NSW strata buildings had serious defects, according to the 2025 Strata Defects Research Report, this should give buyers confidence that if something does go wrong, it won't cost them.
"The cost of rectifying defects during occupancy can be more than five times higher than if they are identified during construction," says Joe Andary from building quality specialists SDSS, which has reviewed more than 4000 inspection reports and more than 200 projects.
"Defects typically begin to surface around year three post completion and peak between years six and seven, well after standard building warranties expire.
"The industry has shifted from reactive defect management to proactive direct prevention."
Anderson agrees.
"We appoint a provider to undertake regular assessments during construction, which costs about 1% of the build cost. This means many common issues are prevented.
"You need to make sure the waterproofing is done properly before you lay the tiles. It's better for construction to be slightly delayed than to have major water damage problems arise later," he says.
The insurance policy costs about 2% of the build cost (including broker fees), so the developer/builder is up for about 3% of the value of the construction and that is non-refundable.
This compares with the standard two-year bond that applies to Class 2 buildings, costing 2% of the build cost.
If an independent building inspector files a final report stating that there are no defects after two years, the bond is refunded to the developer.
Once consumers realise the attractions of buying into a building with an LDI policy in place, these apartments may attract a price premium, but Anderson says that's not the reason developers, such as his company, have embraced it.
"We do it because we want to get it right, it's about lifting standards and protecting buyers."
Four ways buyers can protect themselves
1. Check out the builder's or developer's credentials
Make sure the companies behind the project have a proven track record of quality builds and financial solvency.
In NSW, only buy from developers and builders who hold a high rating (at least three stars) on the Independent Construction Industry Rating Tool (iCIRT).
Visit buildings completed by the same builder five to seven years ago and ask strata committee members or residents about long-term waterproofing issues or structural cracking.
2. Be wary of off-the-plan contracts
Hire a property conveyancer to negotiate:
- protective clauses in contracts
- limit material variation margins that allow developers to alter layout sizes or swap high-end materials for cheaper ones
- negotiate to restrict layout shrinkage to less than 2%-3%
- add a clause mandating that substitute fixtures must be of identical retail value
Also watch sunset clauses that can enable a developer to intentionally drag out construction, cancel your contract, and re-list at a higher price.
Check that local State laws require Supreme Court approval or buyer consent before a developer can trigger a sunset termination.
Do not rely on the developer's handover documentation to assume the apartment is defect-free and hire an independent inspector.
3. Investigate any installed or planned for imbedded networks
This is a private utility setup where a single provider buys electricity, gas or hot water in bulk and on-sells it to the building's residents.
While pitched as efficient, they historically lock buyers into monopoly pricing with no real ability to switch providers.
If you're buying off-the-plan, ask to see the details of the embedded network arrangements upfront so you know what you're up for.
Thanks to recent strata reforms, new embedded network contracts are heavily restricted - for instance, NSW caps these contracts to three years, preventing developers from trapping a building for 10 to 20 years.
For completed apartments, mandatory disclosure laws in most States require the existence of an embedded network to be disclosed.
In NSW, for example the existence of an embedded network - including the operator's name and contract terms - must be explicitly stated on the Section 184 Strata Certificate.
4. When buying an existing apartment get a strata report and a building inspection
The strata report covers the history of the building, including past and current defects and disputes.
It also covers the financial health of the building, the size of the sinking fund, ongoing levies and any special levies.
The building inspection discloses any physical defects and identifies problems that need immediate repairs.
Get stories like this in our newsletters.