This global cement giant could rally 23%
Cheap, cashed up and returning more cash to shareholders, Buzzi could offer investors exposure to global infrastructure growth at a discounted price.
Listed on the Milan stock exchange, Buzzi (Buzzi SpA - BIT: BZU) is an Italian family-controlled cement producer with a diversified portfolio of assets across the US, Italy, Germany, Eastern Europe, Brazil and the UAE, as well as a significant Mexican joint venture. The US is its most important market.
Why Buzzi shares look undervalued
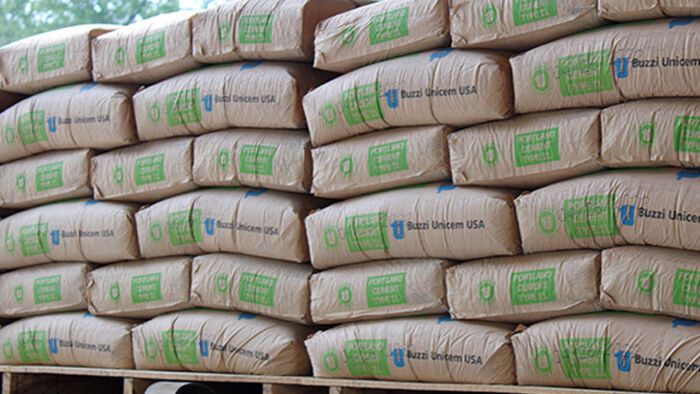
Cement has attractive local economics: plants are highly capital intensive, difficult to permit and costly to replicate, while high transport costs create meaningful barriers to entry.
Still controlled by the founding family, Buzzi has an attractive net cash balance sheet, diversified end market exposure (~35% US, ~21% Central EU) and supportive valuation (~8% Free Cash Flow Yield, 0.9x Book Value).
Buzzi is cheap on an asset basis, with enterprise value of around €125 per tonne of cement capacity. This looks attractive given the group's substantial US exposure, where recent cement transactions have occurred at more than $300 a tonne.
At the current share price of €37.85, with a Market cap of €8.5 billion, Buzzi trades on just 8.4x 2026E EPS of €4.50 and 0.9 Book value.
We think shares are worth high-€40s or ~23% above current levels.
Buzzi's growth outlook and cement market trends
The company's mid-year report indicated they do not anticipate any significant changes compared with the macroeconomic and geopolitical environment observed in the first half.
International tensions and persistent economic uncertainty continue to affect markets, mainly through inflationary pressures on operating costs.
In their main geographies, Buzzi expect demand to remain broadly in line with the first six months of 2026.
The group is reducing its carbon intensity, with net Scope 1 emissions falling to around 562kg of CO₂ per tonne in 2025 and a target of below 500kg/t by 2030.
The Carbon Border Adjustment Mechanism (CBAM) should provide some protection by imposing a comparable carbon cost on imported cement, supporting the industry's ability to pass higher carbon costs through to customers.
Dividends, buybacks and shareholder returns
Buzzi generated €4.5 billion of revenue and €1.23 billion of recurring EBITDA in 2025, at a margin of around 27%.
The balance sheet is a key strength, ending 2025 with €1.1 billion of net cash, giving the group substantial flexibility for acquisitions, investment in existing plants and shareholder returns.
Near-term earnings are being held back by weaker construction activity in the US and Germany and higher operating costs, with management guiding to €1.1-1.2 billion of EBITDA in 2026.
In terms of downside, the company is trading below book value today, and on an EV/IC basis at 0.78.
It fell to around 0.6x during the Eurozone crisis and to 0.55x during the 2022 interest rate shock, which we consider to be a reasonable floor on an asset basis for a business.
However, the combination of roughly 0.9x book value and 8.4x earnings makes Buzzi more interesting, while capital returns are becoming more meaningful.
The dividend yield is only around 1.9%, but Buzzi has increasingly supplemented this with buybacks, which have amounted to roughly 2-3% of market capitalisation annually.
This takes total shareholder yield towards 4-5%, while leaving the group with substantial balance sheet capacity.
At 8.4x earnings, Buzzi has an earnings yield of around 11.9%, suggesting significant scope to increase distributions or deploy capital into attractive acquisitions and reinvestment opportunities.
Get stories like this in our newsletters.