Why another rate rise won't make petrol any cheaper
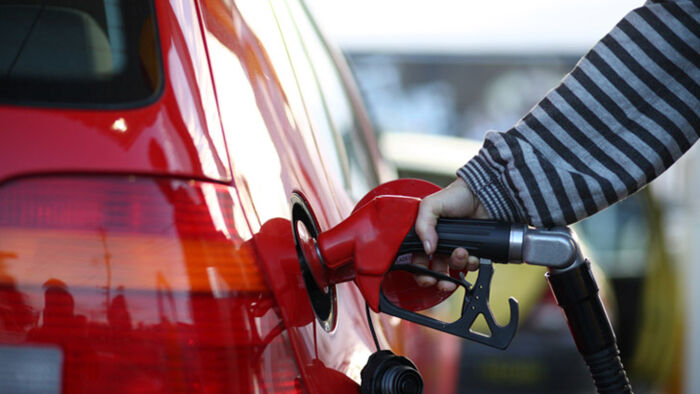
With petrol up 8.7% and electricity prices soaring, households are being told to brace for higher borrowing costs. But would another rate rise actually fix the problem?
How does increasing your mortgage repayments bring down the price of petrol?
This is the question Australians should be asking as inflation hits 4.3% and another interest rate rise enters the conversation. Families are already paying more to fill the car and keep the lights on. Now they could be asked to pay more on their home loan as well.
But what would another rate rise actually achieve?
Transport costs rose 8.7% over the past year, driven by higher global oil prices.
Meanwhile, some housing pressures are easing. The rising cost of building new homes in the 12 months to August 2026 slowed from 5.4% to 4.7% in the 12 months to September 2026. That doesn't mean homes are getting cheaper, it means price rises are slowing.
Electricity prices jumped 12.8%, largely because government rebates ended.
Increasing mortgage repayments will not bring those rebates back, just as it will not produce more oil or put extra electricity into the grid.
Higher rates can make people spend less. They can force a family to cancel a holiday, put off buying a car or stop eating out, but that family still needs to drive to work and switch the lights on.
We risk squeezing households harder without fixing the costs driving their bills higher.
If I were sitting at the Reserve Bank's table, I would be asking why households should take another hit before we have established what another rate rise will achieve.
I would hold rates for now and watch whether higher energy costs are spreading into broader price rises.
And if I were in government, I would stop leaving the Reserve Bank to do the heavy lifting while families carry the cost. Raising rates is not the only choice available.
The government needs to show some backbone. Put reliable, affordable energy ahead of political point-scoring.
Get viable projects built, remove duplicated approvals and fix the delays holding up electricity connections. Set public deadlines, name who is responsible and explain every missed target.
Australians do not need another announcement about what might happen years from now.
They need a government prepared to make difficult decisions and be accountable for delivering them.
None of this makes global oil cheaper overnight, but neither does making a family's mortgage more expensive.
Enough is enough. It is weak leadership to keep asking households to tighten their belts while accepting excuses for slow delivery.
Families are making hard choices every week. It is time the government showed the same urgency.
Best and worst sectors
Materials is the best-performing sector so far this week, rising 4.97%, supported by recovering copper prices and hopes of fresh Chinese stimulus.
Real Estate gained 3.41%, as gains in Goodman Group and retail property trusts helped lift the sector.
Information Technology rounded out the top three, up 2.66%, as renewed AI enthusiasm and a strong NEXTDC rebound boosted technology shares.
At the other end of the market, Consumer Discretionary is the worst-performing sector so far this week.
It fell 4.95% as higher inflation and renewed rate-rise fears raised concerns that households will cut back on non-essential spending.
Consumer Staples was the second-worst sector, dropping 4.21% as profit-taking after recent gains, followed by weakness in Coles, Woolworths and Metcash, dragged the sector lower.
Communication Services rounded out the worst performers this week, falling 1.46%, as rate-rise fears may have reduced demand for dividend-paying stocks.
It's possible that investors are reassessing their yields against cash and bonds.
Best and worst stocks
Lynas Rare Earths led the ASX Top 100 this week, climbing more than 21% as buyers returned after heavy selling. Its update this week showed stronger revenue and record average selling prices.
Greatland Resources Limited followed, rising more than 15%. Its rise appears to be part of the broader rebound in gold miners.
Paladin Energy rounded out the leading performers, gaining more than 14% as improving uranium prices provided a supportive backdrop.
At the other end, Wesfarmers Ltd was the weakest performer, falling more than 7% as slowing Bunnings sales growth and renewed rate-rise fears heightened concerns about consumer spending.
JB Hi-Fi followed, falling more than 6% due to falling Australian sales, with weaker comparable sales reinforcing concerns that households are cutting discretionary purchases.
Woolworths Group Limited rounded out the worst performers, falling more than 5% despite stronger supermarket sales.
Warnings of a tougher Christmas trading period and declining Big W sales highlighted the continued pressure on household spending.
All Ordinaries Index update
The All Ordinaries Index is on track for its strongest week in four months, up 1.2% as of Thursday's close.
Materials led the charge with a sharp rebound, supported by strength in information technology, while financials held slightly positive.
That's pushed the market back above the key 9000-point level. The question now is: can it stay there?
If buyers maintain control, 9200 is the next level to watch.
But a sharp sell-off next week would raise the risk that this is simply a dead-cat bounce, putting a fall towards 8600 back on the table.
There's certainly no shortage of potential triggers, with the RBA's interest rate decision, US midterm elections and earnings from the biggest AI companies all approaching.
One possibility is that investors have already priced in another rate rise and are looking beyond it, betting it could be the last for a while.
But rather than getting caught up in predicting the headlines, watch how the market responds.
For now, the price action is looking more positive. Buyers have stepped in, the market has reclaimed 9000, and momentum has improved.
The next test is whether buyers can defend that level and build on this week's gains.
It's too early to declare the danger is over, but after months of uncertainty, this is a welcome step in the right direction.
Get stories like this in our newsletters.