One shareholder's question changed how I view microcaps
A challenging question from a long-term shareholder became the biggest lesson of the Australian Microcap Investment Conference. Here are five ASX microcaps that stood out, and the investing mistakes they highlight.
You can walk out of an investment conference convinced you have found the next big thing.
A company may have an exciting product, an ambitious management team, and a market that could be worth millions or even billions.
But can you tell whether its shares are worth buying, or are you simply convinced by the presentation?
That question stayed with me after attending the Australian Microcap Investment Conference last week.
What is a microcap?
Microcaps are companies with a market capitalisation of less than $500 million that are listed on the Australian Securities Exchange (ASX).
They can be faster-growing and more innovative than large-cap companies, but they are often higher risk and more volatile.
The range of businesses was impressive, from online marketplaces, biotech, investment apps, a distillery, security monitoring, antiviral treatments, to Gold and other resource projects.
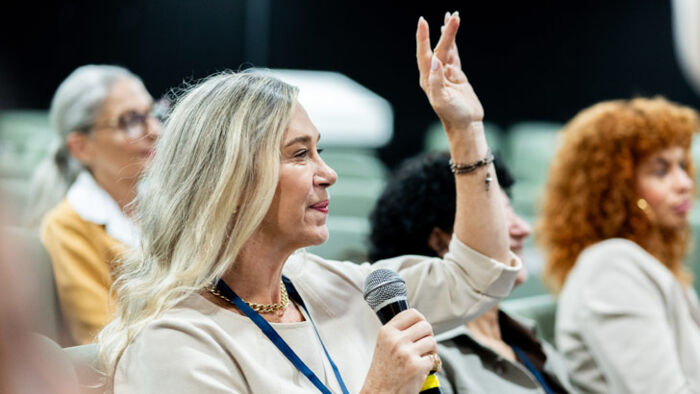
Yet the most valuable moment came when an audience member challenged one company with its prolonged share-price decline and profitability.
The question came from a long-term shareholder, and it exposed a problem investors cannot afford to ignore.
Five ASX microcap stocks and the lessons they teach investors
- Freelancer (ASX: FLN) - Online freelancing and payments platform
- Island Pharmaceuticals (ASX: ILA) - Antiviral drug development
- Intelligent Monitoring Group (ASX: IMB) - Security and monitoring services
- Entropy Neurodynamics (ASX: ENP) - Psychedelic-assisted mental health treatments
- Aureka (ASX: AKA) - Victorian gold exploration and development
Key lesson: A good company story is not enough. Investors also need a plan for when to buy, when to sell and how to manage risk.
Understanding what a company does is only part of the job.
You also need the knowledge to assess whether it can deliver returns, the skill to judge when buyers are taking control, and a plan for what you will do if you are wrong.
If this investor had those skills, they wouldn't have held this company for all those years, only to lose money and live in hope.
This is why investor education matters.
Researching a company is useful, but it does not automatically teach you how to invest. A compelling presentation can leave you informed about the business yet poorly equipped to decide whether to buy its shares.
The attraction is understandable: investing in microcap stocks can be very profitable, but their volatility can also magnify an uneducated investor's mistakes.
Having capital to invest does not compensate for a lack of knowledge, a weak strategy, or poor execution.
What follows are five companies from the conference that illustrate what I am alluding to. Each has a story worth investigating. Each also presents a lesson about the skills investors need before putting money at risk.
Freelancer (ASX: FLN): The danger of ignoring a downtrend
Freelancer Limited (ASX: FLN) connects businesses with freelancers and also operates Escrow.com and the Loadshift freight marketplace. The company prompted the audience's question about the gap between the business and its share price.
The chart shows why that question mattered. From an early trading high around $2.50 in 2013 to approximately nine cents, the shares have lost roughly 96%.
That doesn't mean there were no rallies along the way, but the long-term trend has been down.
Nine cents is now an important area to watch. If buyers cannot defend it, the low price offers no protection against another fall. The share that drops from ten cents to five cents still loses half its value.
The lesson is to recognise a downtrend before committing your capital. Knowing the company's products or believing in their potential does not tell you whether the market agrees.
You need rules to recognise when your original strategy is no longer working. It's a sober reminder that even an established platform with millions of users can struggle to translate its business into shareholder returns.
Island Pharmaceuticals (ASX: ILA): Potential versus timing
Island Pharmaceuticals Limited (ASX: ILA) is developing antiviral treatments through ISLA-101, targeting dengue and other mosquito-borne diseases, and galidesivir, targeting serious viral infections.
The potential benefits extend well beyond shareholders, but clinical development, regulation and funding still determine the path to commercial returns.
Its chart provides a useful contrast to Freelancer. After losing around 90% from its early trading levels, this is a classic example of an IPO that lost most of its value after listing before staging a substantial recovery. More recently, it has since pulled back approximately 50% from its November 2025 high.
A fall of that size may attract bargain hunters, but it does not establish that the shares are undervalued or ready to rise. Investors need to distinguish a pullback within a recovery from renewed weakness. The next buying response will help reveal which is developing.
Potential investors need to ask better questions here as the answers will determine whether they have a good investment or are taking unnecessary risks.
Questions such as, what milestones could change the business? How much funding might be needed? What price behaviour would justify an entry? A treatment's scientific promise and the timing of an investment require different assessments.
Ultimately, the price action from its current level will help reveal whether buyers are prepared to step back in or whether the market remains unconvinced. Either way, now is the time to wait and see rather than jump in because of a good story.
Intelligent Monitoring Group (ASX: IMB): Why a promising business isn't enough
I was impressed by Intelligent Monitoring Group Limited (ASX: IMB), which operates security, fire safety and monitoring businesses across Australia and New Zealand.
Professionally monitored security and the potential use of AI offer avenues for development.
I was also impressed by their presentation last year and the year before that. In 2024 the share price rose around 27% and in 2025 around 26%, whilst this year it fell over 21%.
Over the nearly three years, there has been growth of around 25%, which is quite acceptable, but given the presentations over those years, investors may have been hoping for much more.
The business still needs to convert their opportunities into sustained earnings, and I am one who believes this will occur and we will see IMB do well.
I am just not investing in it right now as it is still a little too early. Why do I think this?
Focusing on the chart from 2022 onwards, 45 cents stands out as an important support level. The shares have been trading within a relatively contained range, while volume has picked up. That makes the area worth monitoring for evidence that buyers are prepared to support the price.
However, higher volume alone does not tell you when to buy. It measures trading activity and needs to be interpreted alongside price.
Investors must learn to assess whether demand is strengthening, whether support is holding and what would confirm a more sustained recovery.
Being interested in a growing industry is a starting point.
Developing the skill to interpret the market's response is what allows you to turn that interest into a considered decision.
Entropy Neurodynamics (ASX: ENP): The cost of waiting for a breakout
Entropy Neurodynamics Limited (ASX: ENP) is developing psilocin-assisted treatments delivered alongside psychotherapy.
Psilocin is the active metabolite of psilocybin, the compound associated with psychedelic mushrooms.
The approach deserves assessment of clinical evidence, regulatory progress and commercial practicality rather than assumptions about recreational drug use.
This stock is also one I saw present last year and is in much the same situation as IMB. The chart shows a stock that has spent much of the past three years moving sideways, repeatedly returning to around three cents and moving up to over four cents.
During this sideways move, several times the price moved up and down 40% to 60%.
Upwards moves of this magnitude attract those looking for quick returns and often those investors are disappointed as they enter near the end of each move.
The current sideways pattern suggests buyers and sellers have yet to establish a sustained direction even though their story is quite compelling.
For an investor, the issue is not simply whether the treatment could succeed. It is how long capital might remain committed while the company develops it. A business can make progress without providing an attractive return over your investment time frame.
An educated investor learns to distinguish patience supported by a strategy from holding indefinitely in hope.
A meaningful change in price behaviour could make Entropy more interesting, but the company's potential alone does not settle when to invest.
Aureka (ASX: AKA): Knowing when a rising share is worth buying
Aureka Limited (ASX: AKA) offers a different opportunity through its Victorian gold portfolio.
Its announced mine and mill acquisition is intended to add the operating Fiddlers Creek gold and silver mine and Wedderburn processing mill, alongside development projects including Irvine and Comstock.
Using existing infrastructure could provide a pathway to production without building everything from scratch.
Investors still need to assess acquisition execution, funding, operating costs and whether resources can become profitable production and cash flow.
The share price has already demonstrated how quickly sentiment can shift, with the chart showing a rise of around 140% since July.
The 20-cent level remains important in my analysis. A sustained break above could indicate that the shares are moving into a higher trading range.
Right now, we need to take the opportunity to assess where price might move, rather than use the recent price action as a reason to chase a recent winner.
You need to know how to recognise a credible breakout, whether it is sustainable and assess the risk of a failed move.
Investors also need to determine whether the potential return justifies that risk.
A rising share requires a strategy just as much as a falling one, and the recent move highlights just how quickly microcaps can move and why following the price action is so important.
From my perspective, AKA looks interesting, but I caution investors not to jump too early. For me I would like to see a sustained break above $0.20 signal that the share price is ready to move to much higher levels.
The biggest mistake ASX microcap investors make
The question I would put to anyone considering Microcap companies is simple: can you explain why you would buy, what evidence supports your timing and what would make you sell?
If you cannot, more enthusiasm for the company will not fill the gap in your knowledge.
Before investing, learn how to assess financial strength and funding needs, identify the prevailing price trend, and build entry and exit rules you can test.
With microcaps, you also need to understand liquidity: getting into a position can be easier than getting out at the price you expect.
These are skills that take education and practice.
Reading a few company announcements, following tips or watching presentations is not a substitute for learning how to make and manage investment decisions.
Education will not eliminate losses, but it gives you a method for assessing uncertainty instead of reacting to it.
The aim is to make decisions you can explain and repeat, rather than depend on somebody else's confidence. There is certainly potential among microcaps, but investors need to understand that potential doesn't always translate into returns quickly.
Finding an interesting microcap is the beginning. Before you buy its future, make sure you have developed the skills to judge the opportunity and protect your capital if it does not unfold as expected.
Get stories like this in our newsletters.