The superannuation moves worth $970,000 in retirement
Every dollar counts in retirement, but new research suggests that Australians could be missing out on hundreds of thousands of dollars in retirement savings without realising it.
Modelling from UniSuper has revealed that people who receive ongoing financial advice during their working lives could retire with up to $970,000 more in their superannuation than those who don't.
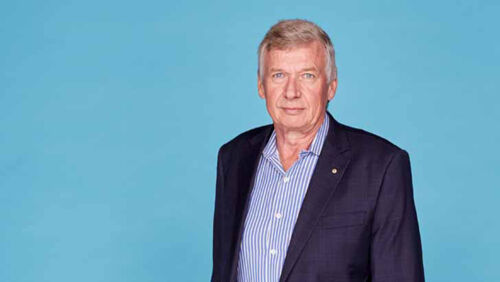
"We talk a lot about compounding investment returns, but we should talk just as much about compounding good financial decisions," says Andrew Gregory, chief advice officer at UniSuper.
"That's what this research is designed to explore.
"It's about decisions made over a lifetime. Not just choosing an investment, but staying disciplined, managing costs, contributing consistently and turning savings into a sustainable retirement income."
From choosing the right investment option to keeping fees in check, the research identified a number of factors that can have a major impact on retirement savings.
Here are four super moves that could make the biggest difference in the lead up to retirement.
1. Don't panic during market fluctuations
Potential impact: $510,000 extra in retirement
As many Australians will have come to appreciate in recent years, superannuation balances aren't always spared from the ups and downs of the market.
During these periods of volatility, it's easy to make emotionally driven, even rash, decisions if your super balance is heading in the wrong direction.
But as Gregory explains, these decisions can often cost people in the long run.
"We see a lot of mistakes in our business where people react to headlines and abandon a long-term strategy because of that. They also try to time the re-entry into the market."
"The biggest mistake is turning a temporary market fall into a permanent loss. That's by switching into cash when prices have already fallen, and then you miss the recovery on the other side."
2. Select the appropriate investment option
Potential impact: $340,000 extra in retirement
Given that superannuation is often seen as a set-and-forget investment, many members don't reassess their investment settings once they've initially set up their super.
There may be advantages to adjusting your asset allocation though, depending on your investment timeframe and risk appetite.
For example, someone who is younger and has decades to retirement may initially benefit from a higher-growth option rather than something more balanced or conservative.
Ultimately though, Gregory says that the decision will come down to each individual's situation and preferences - which is where advice can prove useful.
"The right investment option is not necessarily the one with the highest recent return. It's the one that gives you the best chance at meeting your goals at a level of risk you can live with."
3. Consider making extra contributions
Potential impact: $190,000 extra in retirement
Employers are required to contribute the 12% super guarantee to eligible employees, but workers can boost their balances even further through salary sacrificing or personal contributions.
Thanks to the power of compounding, even relatively small contributions can snowball.
For instance, UniSuper's modelling found that contributing an additional $1000 a year from the age of 25 until retirement could boost someone's balance by more than $190,000.
"We would argue that time and compounding mean that modest, regular contributions can build into quite meaningful savings," Gregory says.
"But the essentials always come first. Things like having emergency cash, getting rid of expensive debt, household needs, but also being aware of any relevant individual contribution caps."
4. Assess the impact of fees
Potential impact: $180,000 extra in retirement
If voluntary contributions can provide an additional boost to superannuation balances come retirement, hefty fees can have the opposite effect.
The gap between the fees charged by different funds may not seem like much at first glance, but it can prove substantial over time - especially as balances grow larger.
UniSuper found that paying just 0.3% more in annual fees could translate into a $180,000 difference come retirement.
"Fees matter because they compound too," says Gregory.
"The caveat, though, is that it's not simply about what you pay and getting the lowest amount of fees - it's what value you receive after your costs."
Get stories like this in our newsletters.