The hidden retirement costs that catch Australians out
Retirement can come with more financial surprises than many Australians expect. From costly emergencies to family pressures, these are the hidden expenses experts say can erode your savings.
Around 2.5 million Aussies are expected to retire over the next 10 years.
But financial planner Trudy Jenkins from NGS Super believes some in this cohort will be better prepared for unexpected costs than others.
"Baby boomers are much better at having an emergency fund amount," she says.
"I think it's because that generation was often setting some money aside. But my generation, Gen X, is kind of a wing-it generation."
From surprise vet bills to six-figure loans for adult children, some retirement costs can quickly derail even the best-laid financial plans. Here are four hidden expenses experts say Australians often overlook.
1. Pet bills
Desire for an animal companion is something Jenkins says she sees strike many people who've recently called time on their careers.
"When people do ease into that retirement phase, they end up getting a pet for company," she says.
"But they're not thinking about the costs that could come with that."
Jenkins has witnessed the financial toll a trip to the vet for an emergency procedure can take on retirees.
In one case, a couple ended up spending over $10,000 from their savings on several surgeries for their cavoodle within just a few years.
Pet insurance can be costly and rising premiums have grabbed headlines recently, but Jenkins says it is worth considering as a way to cushion you against vet bills.
You can get the most value out of a policy if your pet is still young.
In which case, take out a policy as soon as possible, before your pet develops any underlying ailments insurers may refuse to cover.
2. Emergency repairs
Jenkins says minor home repairs and upgrades can be put off if you're retired and looking to save money.
But sudden major damage will give you no choice but to stump up some cash if you want to keep living in your property
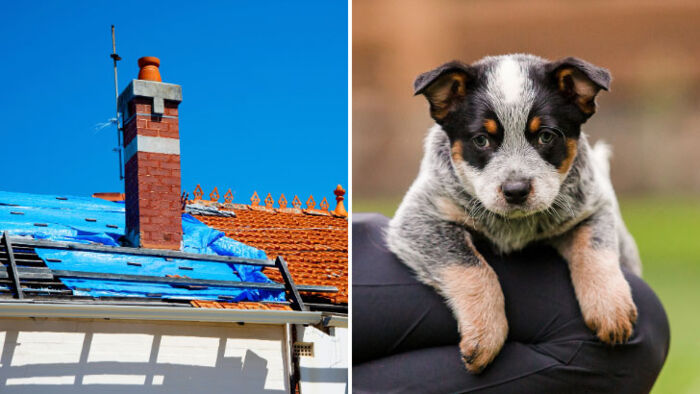
For example, Jenkins recently helped two people manage payments after the roofs of their homes were damaged by wild weather.
"You're looking at $10,000 to $20,000 for a new roof. So that is something that people do not foresee or put into the budget."
She says it's also important to think about whether any ongoing maintenance jobs can build up into something expensive if neglected.
"Things where you might not need to do them very often and you completely forget that they will need maintenance at some stage can be costly."
3. Bank duties
Stories of parents playing bank of mum and dad and dipping into their savings to help adult children are regularly in the news.
Vincent Stranges, retirement specialist at Generation Life says the sums are getting bigger.
"The amount could vary from $25,000 to help pay off some loans or even a HECS debt, to having to help the kids get into the property market," he says.
"$100,000 up and upwards is not uncommon... kids may need help with a home deposit or going through marital issues."
But Stranges says Aussies are taking on bank of mum and dad duties at more advanced ages, causing well-meant lending to clash with their plans for retirement.
"People in that cohort nowadays would've had children later, so those needs [to help kids] that historically would've been an issue 15, 20 years ago are now an issue just before they hit retirement."
Pressure to lend money can even come from later generations, says David Lane, head of wealth advisory at Focus Partners Australia.
"Increasingly, we tend to find a lot of grandparents will fund some or all of their grandchildren's education."
Lane warns older Aussies considering extending this sort of help to think about the expectations it might set.
"If you do that for one [child or grandchild], typically you need to do it for all."
4. Lifestyle creep
Lane says daily expenses are another area where retirees can see their budget get eaten up more quickly than expected.
"Your spending patterns will be different when you are retired, you'll have a lot more time on your hands," he explains.
"A lot of people will say: okay, well, I'll spend similar amount as I've been spending while working. But sometimes when you're at work, you're restrained from spending."
He said retirees have a lot more time for new hobbies and pastimes.
"Things like gym or golf club memberships and going out to lunches more regularly than you would when you're at work. Those sorts of things need to get factored into the budget."
What can you do?
Experts say building up a buffer of cash savings is a straightforward way to prepare for any of these costs.
But it's worth putting a figure on potential expenses where possible, to know what you should be working towards.
To prevent lifestyle creep, think about what you'll actually be doing in retirement.
"Think about what your lifestyle will be and factor in things like holidays," Lane says.
"Obviously, you've got a lot more time and one of the main goals of a lot of people when they retire is to travel more, so actually put that into the budget as well."
Itemising potential costs around the home can help you prepare for any sudden home repairs that might crop up.
"Go around your house room by room and look at the potential items that will need upkeep or maintenance.
"[Think about] whether or not your house will need a repaint in five years' time or whether you need a new toilet, bathroom, fridge or washing machine."
It's also worth looking at income products like annuities.
These are investment products that take your cash and turn it into a regular income stream for life.
They can be structured to pay you more money earlier in retirement, when you're living a more expensive lifestyle, instead of holding too much back for when you're older and less active.
Get stories like this in our newsletters.